Vehicle & Project Proposal
eTuk USA identifies the platform, approved configuration, included equipment, delivery scope and written price.
Request a proposal →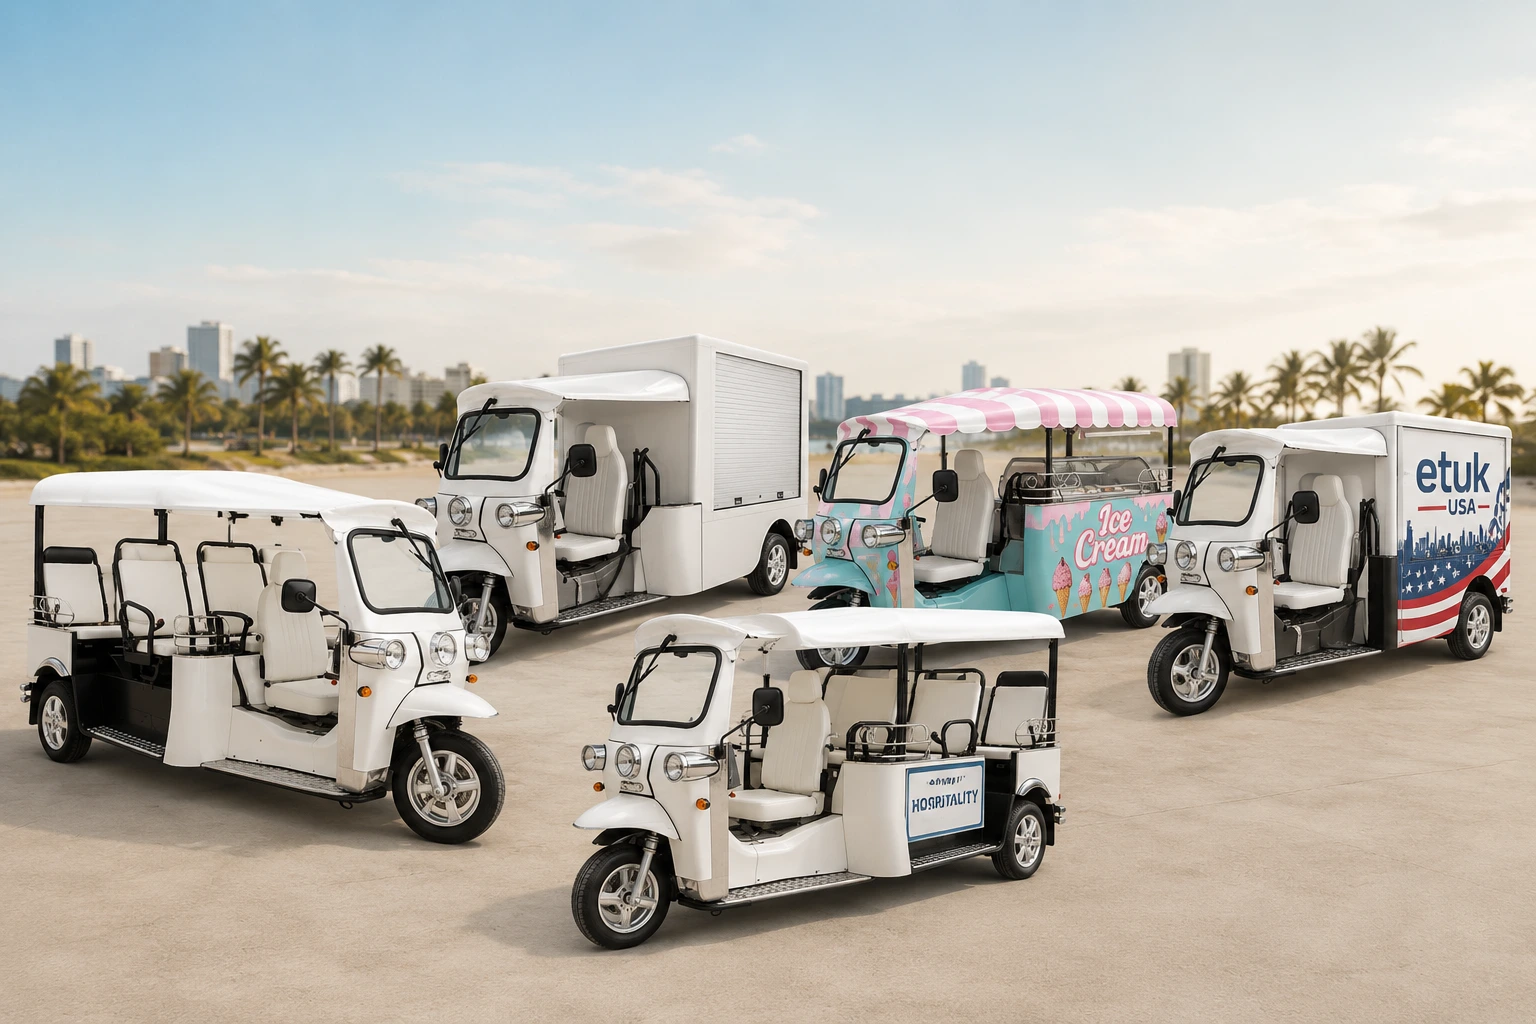
Financing preparation for qualified buyers
eTuk USA helps qualified buyers explore available financing pathways after the vehicle, configuration and project price are defined in a written proposal. Financing is not guaranteed: the provider determines eligibility, down payment, amount financed, rate, term, payment, fees, collateral or guarantees, funded items and approval conditions.
eTuk USA is not promising approval, a monthly payment or a specific rate on this page. Review all financing documents directly with the provider and obtain professional financial, tax or legal advice when needed.
How financing fits the purchase
A general vehicle price is not enough. The financing request should match the exact vehicle and clearly separate other launch costs.
eTuk USA identifies the platform, approved configuration, included equipment, delivery scope and written price.
Request a proposal →The provider determines required documents, eligibility, approval, structure, terms, security and funded items.
Ask about available pathways →The buyer evaluates affordability, cash flow, risk, total obligation and whether the financed asset supports the operation.
Review financing terms →Vehicle price before financing
Public MSRP is a planning reference, not a financing approval or a complete statement of what a provider will fund.
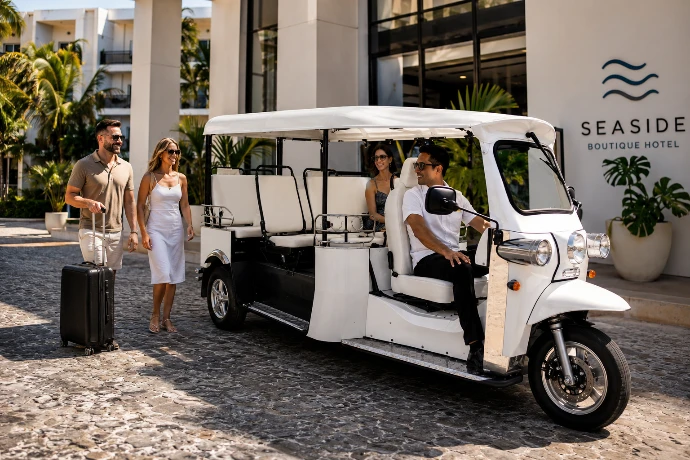
The exact amount requested for financing may differ after options, delivery and other included project items are defined.
Passenger details →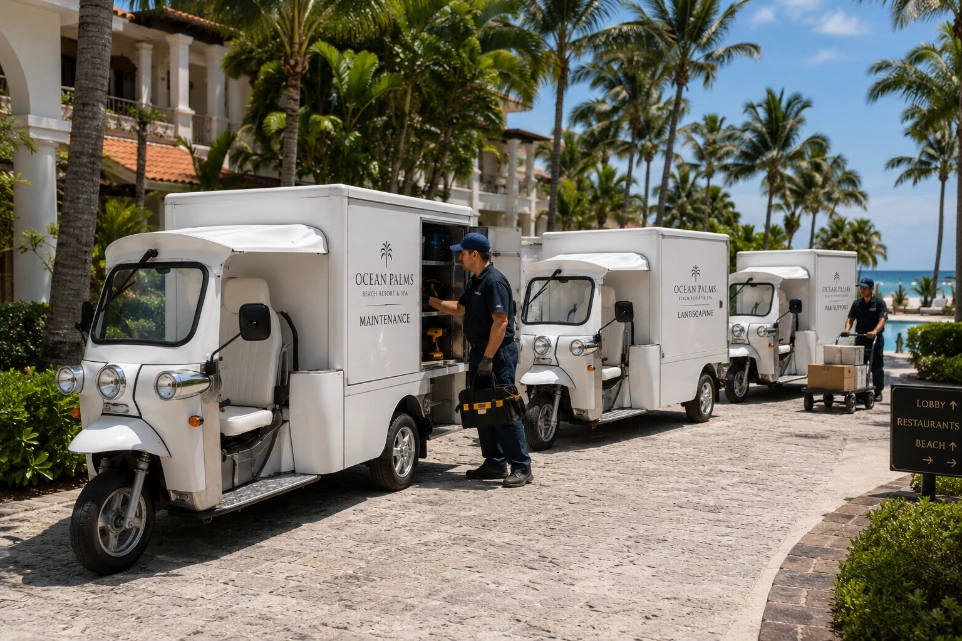
Special body equipment, delivery and deployment costs must be identified before the financing request is finalized.
Cargo details →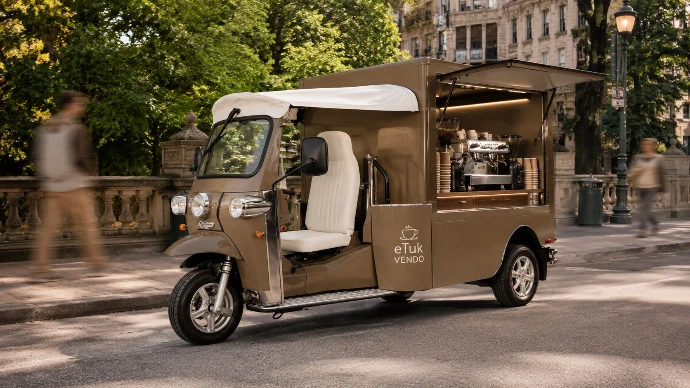
Vehicle, body, commercial equipment and launch costs may be treated differently by a provider. Confirm eligible funded items directly.
Vendo details →Application readiness
Requirements vary. Ask the provider for its exact checklist before submitting confidential information.
Legal name, entity type, EIN, address, ownership, authorized signer and time in business.
Exact vehicle, configuration, equipment, price, delivery, seller and intended use.
Business and, when applicable, owner information or authorizations requested by the provider.
Bank statements, tax returns, financial statements or other records requested for underwriting.
Business plan, operating assumptions, projections and explanation of how the asset supports repayment.
Source and availability of the required buyer contribution, if one is required.
Insurance, collateral, lien or guarantee information required by the provider.
Application, documentation, conditions, funding timing and expiration of any approval.
Cash flow before monthly payment
A monthly payment can appear manageable while the complete project is underfunded. Build a conservative cash-flow plan that includes down payment, non-financed launch costs, operating reserve, charging, insurance, staffing, maintenance, taxes and seasonal or demand variability.
Financing term review
Terminology and disclosures can vary by provider and transaction. Ask questions until every material term is understood in writing.
| Term | What to confirm | Why it matters |
|---|---|---|
| Amount financed | Exact financed amount and which vehicle, equipment, delivery or fees it includes. | Prevents the buyer from assuming unfunded launch costs are covered. |
| Down payment | Amount, due date, refundable status and source requirements. | Determines upfront cash needed before delivery or funding. |
| Rate & pricing | Interest rate or financing charge, whether fixed or variable, and how it can change. | Affects payment and total financing cost. |
| Term & payments | Number, amount, frequency, first due date and any irregular or final payment. | Must align with business cash flow and ownership plan. |
| Fees | Application, documentation, origination, closing, filing, servicing or other charges. | Fees can materially change the total obligation. |
| Security | Liens, collateral, personal guarantees, insurance and reporting requirements. | Defines which assets or people support repayment. |
| Prepayment | Whether early payoff is allowed and whether a penalty or minimum charge applies. | Affects refinancing, sale and early payoff decisions. |
| Default | Late charges, cure periods, acceleration, repossession and other remedies. | Defines the consequences if payments or obligations are not met. |
| Total obligation | Total scheduled payments plus required fees and non-financed project costs. | Provides a more complete comparison than monthly payment alone. |
Business in a Box and fleets
A Vendo business or multi-vehicle deployment can include assets and expenses beyond the vehicle. The provider decides what it will finance. Build a source-of-funds plan for every item before committing to the project.
May be evaluated as part of the asset proposal, subject to provider rules and documentation.
Confirm whether logistics, taxes, title, registration or fees are financed or paid separately.
Electrical work, parking, tenant improvements and charging readiness may require separate funding.
Inventory, payroll, permits, marketing and operating reserve may require a separate eligible funding source.
Independent business-funding resources
These official resources are independent of eTuk USA. Eligibility, use of proceeds, approval and terms are determined by the participating program and lender.
The U.S. Small Business Administration explains that eligible 7(a) loan proceeds can include purchasing and installing machinery and equipment, subject to program and lender requirements.
Review SBA 7(a) information →SBA microloans are made through approved intermediary lenders and may support eligible working capital, inventory, supplies, fixtures, machinery or equipment.
Review SBA Microloan information →SBA Lender Match helps businesses prepare information and connect with participating lenders. Matching is not a loan approval.
Explore SBA Lender Match →From vehicle plan to funded purchase
Exact steps vary by provider, but the asset and business case should be clear before application.
Choose the vehicle, job, configuration, delivery and total project scope.
Obtain a written proposal identifying price, inclusions and exclusions.
Gather provider-requested business, credit and financial information.
Submit securely and compare all approval conditions and obligations.
Sign only after terms, funding, vehicle scope and timing are understood.
Electric tuk tuk financing FAQ
These answers are educational and do not replace provider documents or professional advice.
eTuk USA helps qualified buyers explore available financing pathways after the vehicle and project proposal are defined. Financing is subject to provider eligibility, credit approval, documentation, transaction structure and final terms; approval is not guaranteed.
The financing provider makes the credit decision and determines eligibility, down payment, amount financed, rate, term, payment, fees, security, funded items and conditions. eTuk USA defines the vehicle and project proposal.
No universal score is published on this page. Requirements vary by provider, applicant, transaction, business history and other underwriting factors. Ask the financing provider for its current criteria and required authorizations.
The financing provider determines whether a down payment is required and its amount. Do not rely on an estimated percentage unless it appears in the provider's written approval and financing documents.
A payment cannot be calculated accurately without the approved amount financed, down payment, rate or financing charge, term, payment frequency, fees and any final or irregular payment. Review the provider's written terms rather than a generic estimate.
The provider decides which costs are eligible. Confirm separately whether the vehicle, installed equipment, customization, delivery, taxes, title, registration, commercial equipment or other project costs can be included.
Startup eligibility varies by provider and program. A provider may request owner credit information, business plan, projections, experience, down payment, collateral or guarantees. A strong concept does not guarantee approval.
A provider may evaluate the vehicle and eligible installed equipment, but other launch costs may need separate funding. Define the vehicle, build, delivery, permits, site work, inventory, payroll, marketing and operating reserve before applying.
Fleet financing may be available subject to the provider, applicant, vehicle mix, quantity and project. Obtain a written fleet proposal and identify charging, delivery and deployment costs so the financing request reflects the complete plan.
Start by selecting the eTuk direction and requesting a written vehicle or fleet proposal. Then prepare the business and financial information requested by the financing provider and review every approval condition before signing.
Start with the exact eTuk direction, configuration, delivery destination and project scope. We will help prepare the vehicle proposal and explain the available next step for qualified buyers.
Financing preparation for qualified buyers
eTuk USA helps qualified buyers explore available financing pathways after the vehicle, configuration and project price are defined in a written proposal. Financing is not guaranteed: the provider determines eligibility, down payment, amount financed, rate, term, payment, fees, collateral or guarantees, funded items and approval conditions.
eTuk USA is not promising approval, a monthly payment or a specific rate on this page. Review all financing documents directly with the provider and obtain professional financial, tax or legal advice when needed.
How financing fits the purchase
A general vehicle price is not enough. The financing request should match the exact vehicle and clearly separate other launch costs.
eTuk USA identifies the platform, approved configuration, included equipment, delivery scope and written price.
Request a proposal →The provider determines required documents, eligibility, approval, structure, terms, security and funded items.
Ask about available pathways →The buyer evaluates affordability, cash flow, risk, total obligation and whether the financed asset supports the operation.
Review financing terms →Vehicle price before financing
Public MSRP is a planning reference, not a financing approval or a complete statement of what a provider will fund.
The exact amount requested for financing may differ after options, delivery and other included project items are defined.
Passenger details →Special body equipment, delivery and deployment costs must be identified before the financing request is finalized.
Cargo details →Vehicle, body, commercial equipment and launch costs may be treated differently by a provider. Confirm eligible funded items directly.
Vendo details →Application readiness
Requirements vary. Ask the provider for its exact checklist before submitting confidential information.
Legal name, entity type, EIN, address, ownership, authorized signer and time in business.
Exact vehicle, configuration, equipment, price, delivery, seller and intended use.
Business and, when applicable, owner information or authorizations requested by the provider.
Bank statements, tax returns, financial statements or other records requested for underwriting.
Business plan, operating assumptions, projections and explanation of how the asset supports repayment.
Source and availability of the required buyer contribution, if one is required.
Insurance, collateral, lien or guarantee information required by the provider.
Application, documentation, conditions, funding timing and expiration of any approval.
Cash flow before monthly payment
A monthly payment can appear manageable while the complete project is underfunded. Build a conservative cash-flow plan that includes down payment, non-financed launch costs, operating reserve, charging, insurance, staffing, maintenance, taxes and seasonal or demand variability.
Financing term review
Terminology and disclosures can vary by provider and transaction. Ask questions until every material term is understood in writing.
| Term | What to confirm | Why it matters |
|---|---|---|
| Amount financed | Exact financed amount and which vehicle, equipment, delivery or fees it includes. | Prevents the buyer from assuming unfunded launch costs are covered. |
| Down payment | Amount, due date, refundable status and source requirements. | Determines upfront cash needed before delivery or funding. |
| Rate & pricing | Interest rate or financing charge, whether fixed or variable, and how it can change. | Affects payment and total financing cost. |
| Term & payments | Number, amount, frequency, first due date and any irregular or final payment. | Must align with business cash flow and ownership plan. |
| Fees | Application, documentation, origination, closing, filing, servicing or other charges. | Fees can materially change the total obligation. |
| Security | Liens, collateral, personal guarantees, insurance and reporting requirements. | Defines which assets or people support repayment. |
| Prepayment | Whether early payoff is allowed and whether a penalty or minimum charge applies. | Affects refinancing, sale and early payoff decisions. |
| Default | Late charges, cure periods, acceleration, repossession and other remedies. | Defines the consequences if payments or obligations are not met. |
| Total obligation | Total scheduled payments plus required fees and non-financed project costs. | Provides a more complete comparison than monthly payment alone. |
Business in a Box and fleets
A Vendo business or multi-vehicle deployment can include assets and expenses beyond the vehicle. The provider decides what it will finance. Build a source-of-funds plan for every item before committing to the project.
May be evaluated as part of the asset proposal, subject to provider rules and documentation.
Confirm whether logistics, taxes, title, registration or fees are financed or paid separately.
Electrical work, parking, tenant improvements and charging readiness may require separate funding.
Inventory, payroll, permits, marketing and operating reserve may require a separate eligible funding source.
Independent business-funding resources
These official resources are independent of eTuk USA. Eligibility, use of proceeds, approval and terms are determined by the participating program and lender.
The U.S. Small Business Administration explains that eligible 7(a) loan proceeds can include purchasing and installing machinery and equipment, subject to program and lender requirements.
Review SBA 7(a) information →SBA microloans are made through approved intermediary lenders and may support eligible working capital, inventory, supplies, fixtures, machinery or equipment.
Review SBA Microloan information →SBA Lender Match helps businesses prepare information and connect with participating lenders. Matching is not a loan approval.
Explore SBA Lender Match →From vehicle plan to funded purchase
Exact steps vary by provider, but the asset and business case should be clear before application.
Choose the vehicle, job, configuration, delivery and total project scope.
Obtain a written proposal identifying price, inclusions and exclusions.
Gather provider-requested business, credit and financial information.
Submit securely and compare all approval conditions and obligations.
Sign only after terms, funding, vehicle scope and timing are understood.
Electric tuk tuk financing FAQ
These answers are educational and do not replace provider documents or professional advice.
eTuk USA helps qualified buyers explore available financing pathways after the vehicle and project proposal are defined. Financing is subject to provider eligibility, credit approval, documentation, transaction structure and final terms; approval is not guaranteed.
The financing provider makes the credit decision and determines eligibility, down payment, amount financed, rate, term, payment, fees, security, funded items and conditions. eTuk USA defines the vehicle and project proposal.
No universal score is published on this page. Requirements vary by provider, applicant, transaction, business history and other underwriting factors. Ask the financing provider for its current criteria and required authorizations.
The financing provider determines whether a down payment is required and its amount. Do not rely on an estimated percentage unless it appears in the provider's written approval and financing documents.
A payment cannot be calculated accurately without the approved amount financed, down payment, rate or financing charge, term, payment frequency, fees and any final or irregular payment. Review the provider's written terms rather than a generic estimate.
The provider decides which costs are eligible. Confirm separately whether the vehicle, installed equipment, customization, delivery, taxes, title, registration, commercial equipment or other project costs can be included.
Startup eligibility varies by provider and program. A provider may request owner credit information, business plan, projections, experience, down payment, collateral or guarantees. A strong concept does not guarantee approval.
A provider may evaluate the vehicle and eligible installed equipment, but other launch costs may need separate funding. Define the vehicle, build, delivery, permits, site work, inventory, payroll, marketing and operating reserve before applying.
Fleet financing may be available subject to the provider, applicant, vehicle mix, quantity and project. Obtain a written fleet proposal and identify charging, delivery and deployment costs so the financing request reflects the complete plan.
Start by selecting the eTuk direction and requesting a written vehicle or fleet proposal. Then prepare the business and financial information requested by the financing provider and review every approval condition before signing.
Start with the exact eTuk direction, configuration, delivery destination and project scope. We will help prepare the vehicle proposal and explain the available next step for qualified buyers.